Auro Anantha EMI calculator
Featured Image of Auro Anantha EMI calculator


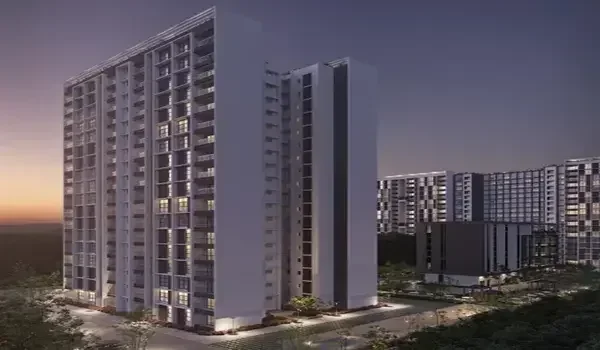
The Auro Anantha EMI calculator shows that buying a 4 BHK flat priced from ₹4.80 Crore in Raidurg takes a monthly payment of ₹3,33,322 with an 80% loan of ₹3.84 Crore at an 8.50% interest rate over 20 years. This online tool gives you the exact split between loan interest and principal sum for homes in this project. The gated community features two 54-floor towers on 3.5 acres of land.

You can pick other loan terms to suit your monthly cash flow. A longer 30-year loan brings down your monthly payment to ₹2,95,263. A faster 15-year loan raises the monthly payment to ₹3,78,074, but it cuts your total interest cost by ₹1.19 Crore.

This simple tool helps you plan your own 20% down payment of ₹96 Lakh with ease. It also helps you track building stage payments until final home keys arrive in December 2030.
What Is the Auro Anantha EMI Calculator?


The Auro Anantha EMI calculator is an online tool that finds your exact monthly bank payment for homes in this project using standard loan math. It breaks down every single monthly payment into loan interest and principal parts.

EMI = [P × r × (1 + r)^n] / [(1 + r)^n - 1]

In plain words:

  • P = Loan Amount (Principal)
  • r = Monthly Interest Rate (Annual Rate ÷ 12 ÷ 100)
  • n = Loan Tenure in Months
  • ^n = Raised to the power of n

Auro Anantha Loan Eligibility and Unit Price Assessment


Base prices at Auro Anantha start from ₹4.80 Crore for large 4 BHK flats of 3,600 to 3,800 sq ft in Raidurg. Top Indian banks lend up to 80% of the flat cost for high-value luxury homes.

Apartment Configuration Super Built-Up Area (Sq Ft) Starting Indicative Price Self-Funded Down Payment (20%) Max Eligible Loan Value (80%)
4 BHK (Type A) 3,600 sq ft ₹4,80,00,000 ₹96,00,000 ₹3,84,00,000
4 BHK (Type B) 3,700 sq ft ₹4,93,33,000 ₹98,66,600 ₹3,94,66,400
4 BHK (Type C) 3,800 sq ft ₹5,06,66,000 ₹1,01,33,200 ₹4,05,32,800

Estimated Monthly EMI Scenarios Across Different Tenures


Your chosen loan tenure directly changes your monthly cash needs and your total lifetime interest bill. The numbers below use an 80% loan of ₹3.84 Crore on the base ₹4.80 Crore price at an 8.50% yearly interest rate.

Loan Term Months Monthly Pay (EMI) Total Interest Total Bank Pay
10 Years 120 ₹4,76,275 ₹1,87,53,047 ₹5,71,53,047
15 Years 180 ₹3,78,074 ₹2,96,53,303 ₹6,80,53,303
20 Years 240 ₹3,33,322 ₹4,15,97,370 ₹7,99,97,370
25 Years 300 ₹3,09,112 ₹5,43,33,524 ₹9,27,33,524
30 Years 360 ₹2,95,263 ₹6,78,94,845 ₹10,62,94,845

Step-by-Step Guide to Calculating Your Instalment


Good home loan planning means adding government taxes and project fees to your basic flat cost. You can find your exact monthly payment by taking these four simple steps.

  • Find the Full Cost: Add state stamp duty (7.5%), registration fee, 5% GST, and club fees to the base price of your flat.
  • Set Your Down Payment: Take away your cash down payment (at least 20% of the total price) from the full home cost.
  • Check Bank Rates: Ask trusted retail lenders like SBI, HDFC Bank, ICICI Bank, or Axis Bank for your loan interest quote.
  • Pick Your Loan Years: Enter the loan sum, interest rate, and years into the online calculator to see your monthly payment.

Key Financial Factors That Influence Your EMI


Your home loan interest rate and monthly payment depend on your income and your credit profile. Keeping track of these key items will help you secure the best borrowing deal.

  • Good CIBIL Score: A score of 750 or higher gets you the lowest loan interest rates of 8.40% to 8.60%.
  • Income Share Cap: Banks want all your monthly debt bills to stay below 50% to 55% of your net monthly pay.
  • Bigger Down Payment: Paying 25% or 30% upfront cuts your borrowed loan sum and saves you money on interest over time.
  • Repo Rate Moves: Floating-rate loans shift up or down whenever the Reserve Bank of India moves its benchmark repo rate.

Pre-EMI vs Full EMI Repayment Options During Construction


Pre-EMI plans let you pay interest only on the money given to the builder at each building step until December 2030. In contrast, Full EMI starts paying down both the loan balance and interest right away from month one.

  • Pre-EMI Plan:
  • Monthly payments stay small and light during early construction work.
  • You keep extra cash in hand while the twin 54-storey towers go up.
  • The main loan sum does not drop until final handover in December 2030.
  • Full EMI Plan:
  • Monthly pay stays the same and starts higher from the first day.
  • It cuts down the main loan balance from month one.
  • You save a very large sum of cash on total loan interest over time.

Construction-Linked Disbursement Schedule Impact on EMI


Construction-linked plans release bank funds in small steps tied directly to real building work on site. This keeps your money safe and ties your monthly loan bills to visible site progress.

  • Booking Step (10% to 20%): You pay this upfront from your own cash to sign the sale agreement.
  • Basement Work (10%): The lending bank sends its first release, which starts your small Pre-EMI monthly charges.
  • Floor Slabs (40% to 50%): The bank sends out money as the 54 tower floors go up, making monthly Pre-EMI grow step by step.
  • Final Handover (Last 10% to 20%): The last loan sum goes out when occupancy papers come in December 2030, shifting the loan to full monthly EMI.

Tax Deductions and Net EMI Outlay Analysis


Tax rules under the Indian Income Tax Act help reduce your real out-of-pocket home loan cost each year. Salaried staff and business owners can claim tax rebates on both the interest and principal parts of their loan.

  • Section 24(b) - Interest Relief: You can deduct up to ₹2,00,000 every year on home loan interest for your own home.
  • Section 80C - Principal Relief: You can claim up to ₹1,50,000 each financial year on the principal paid back under the old tax system.
  • Joint Loan Perks: Buying with a working spouse lets both co-borrowers claim separate tax cuts, doubling your household savings.

Effective Strategies to Reduce Your Monthly EMI Outlay


Using smart money habits will help lower your total loan interest bill across a 20- or 30-year term. Small, steady steps during your loan life bring great financial relief.

  • Make Part Pre-Payments: Use work bonuses or extra cash to pay down your loan balance directly.
  • Put More Down Upfront: Paying 25% or 30% down rather than 20% lowers your loan sum and shrinks your monthly bill.
  • Ask for Rate Cuts: When the Reserve Bank cuts benchmark repo rates, make sure your bank drops your loan rate too.
  • Cut Down Loan Years: Keep your monthly pay the same while paying extra principal each year to wipe out years of debt fast.

Frequently Asked Questions (FAQs)


1. What is the expected monthly EMI for a 4 BHK flat in Auro Anantha?

The monthly payment starts near ₹3,33,322 for a 20-year loan at 8.50% interest on an 80% loan of ₹3.84 Crore. Your final payment changes with your down payment, bank interest rate, and chosen years.

2. What minimum down payment is needed to book a flat?

You must pay at least 20% down from your own pocket (starting at ₹96 Lakh for a ₹4.80 Crore unit), as banks lend up to 80%.

3. What is the difference between Pre-EMI and Full EMI during construction?

Pre-EMI means you pay only the interest on the loan amount the bank has released to the builder. You usually pay this amount during construction. With a full EMI, you pay both the loan amount and interest from the start. The right option depends on your loan terms and financial needs.

4. Does the home loan EMI cover government fees and taxes?

A home loan usually covers the amount approved by the bank for the property. Buyers may need to pay GST, stamp duty, and registration fees separately. Check with your bank to confirm which costs are covered by your loan.

5. When will the official RERA carpet area and cost sheets be available?

The builder plans to release the full cost sheets and carpet area details during the official launch in November 2026. The pre-launch phase is planned for October 2026. Buyers should confirm these details with the builder and check the approved project documents before booking.

Enquiry
Enquire Now